A certificate is only worth what stands behind it. With more firms than ever offering spray foam removal, paperwork quality varies wildly, and that difference decides whether your mortgage moves. Here's how to judge what you're being offered, or what you've already got.
Key takeaways
- The big red flags: a certificate issued without a post-removal inspection, no photographic evidence, and promises that every lender will accept it.
- A genuine pack contains four things: the certificate, an independent inspection of the roof timbers, before-and-after photographs, and licensed disposal records.
- If you've already paid and your paperwork falls short, it's fixable: the roof can be re-inspected and properly documented without redoing the removal.
Why certificate quality decides your mortgage
Lenders don't refuse spray-foamed homes out of stubbornness. They refuse because their valuer can't inspect the roof timbers. So the paperwork that reverses a refusal has to do one job: prove the foam is gone and the structure has been looked at by someone qualified.
A certificate that doesn't do that job is decoration. Homeowners regularly discover this at the worst moment, when the buyer's surveyor or the lender's valuer asks a question the paperwork can't answer, and the transaction stalls a second time. The documentation lenders actually need is well understood; the gap is in what some firms hand over.
The red flags to check
Whether you're comparing quotes or holding paperwork from a job already done, check for these:
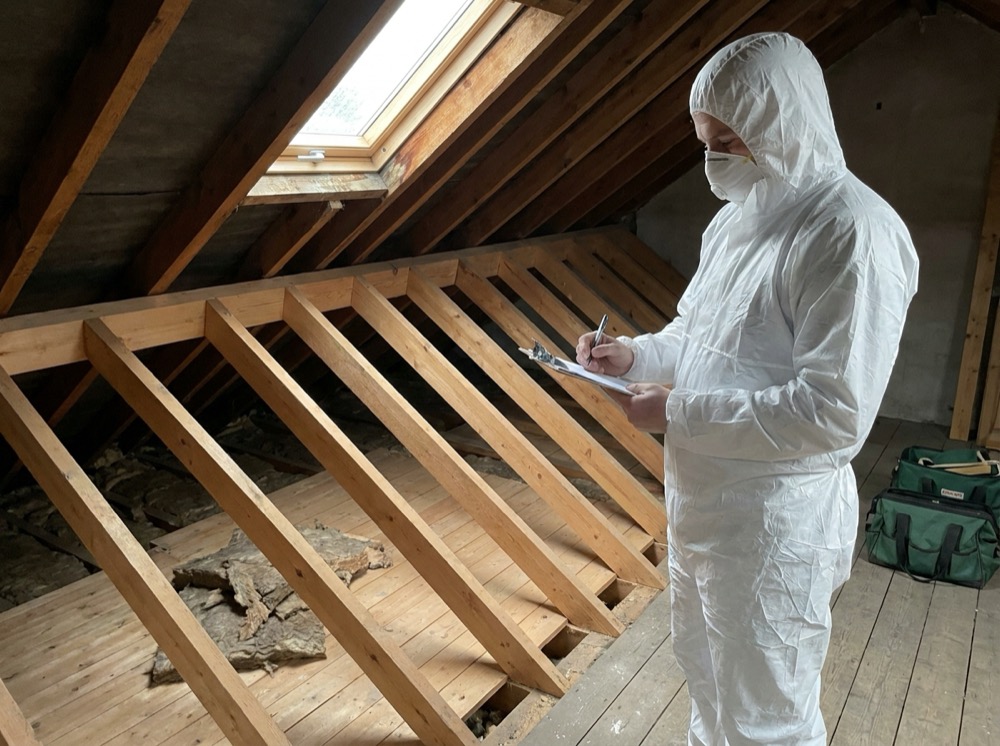
- No post-removal inspection. If the certificate was issued without anyone inspecting the exposed roof timbers, it can't answer the lender's structural question.
- No photographic evidence. A genuine pack shows the roofline before, during and after. No photos means the surveyor has to take the firm's word for it, and surveyors don't.
- Promises of universal acceptance. "Accepted by all lenders" or "100% approval" should end the conversation. Lender criteria differ and change; no honest firm can promise every sign-off in advance.
- Official-sounding standards nobody publishes. Some paperwork cites impressive-looking "removal standards". Check who's behind them: if no recognised professional body publishes the standard, it carries no weight with a surveyor.
- A fixed price and certificate promised sight-unseen. Nobody can price a removal, let alone certify a roof, without seeing it.
- No waste documentation. Spray foam is controlled waste. If there's no record of licensed disposal, that's a corner cut where you can see it, and others where you can't.
What a genuine evidence pack contains
The real thing is a set of documents, not a single sheet: a signed removal certificate identifying the property, dates and specialists; an independent inspection report on the condition of the roof timbers, prepared to the standards chartered surveyors work to; the full photographic record; licensed waste disposal documentation; and itemised invoices for any remedial work. Our certificate and evidence pack page breaks down each document and how lenders use it.
Already paid, and worried about your paperwork?
This is one of the most common situations we hear about, and it's fixable without paying for the removal twice. A specialist inspects the roof space, confirms the removal is complete (or finishes what was left), documents the condition of the timbers and issues the certificate and evidence pack your lender needs.
Don't go back to your lender with weak paperwork and hope. A second refusal makes the third conversation harder. Get the documentation right, then go back once.
The 60-second check
Before you accept any certificate, ask three questions. Was the roof inspected after the foam came off, by whom, and is it in writing? Are there before-and-after photographs of the actual roofline? Is the waste disposal documented under a carrier's licence? Three yeses and your paperwork will survive scrutiny. Anything else, keep asking. Check your eligibility in 60 seconds using the button below and we'll put the real thing in your hands.